How Malaysian Parents Can Budget for Overseas Education
Most parents don’t start with a spreadsheet. They start with a number their child mentions after a school talk — “Miss said Melbourne is about RM 80,000 a year” — and a mild sense of panic. If that’s where you are right now, you’re in good company. Every family we’ve sat down with at GoUni started the same way: a rough figure, a lot of questions, and no clear sense of what actually fits their household. This guide walks through how to turn that vague worry into an actual plan, with real figures for the six destinations we work with most — Malaysia, Singapore, Australia, the UK, New Zealand and Ireland.
Working out what the degree will really cost
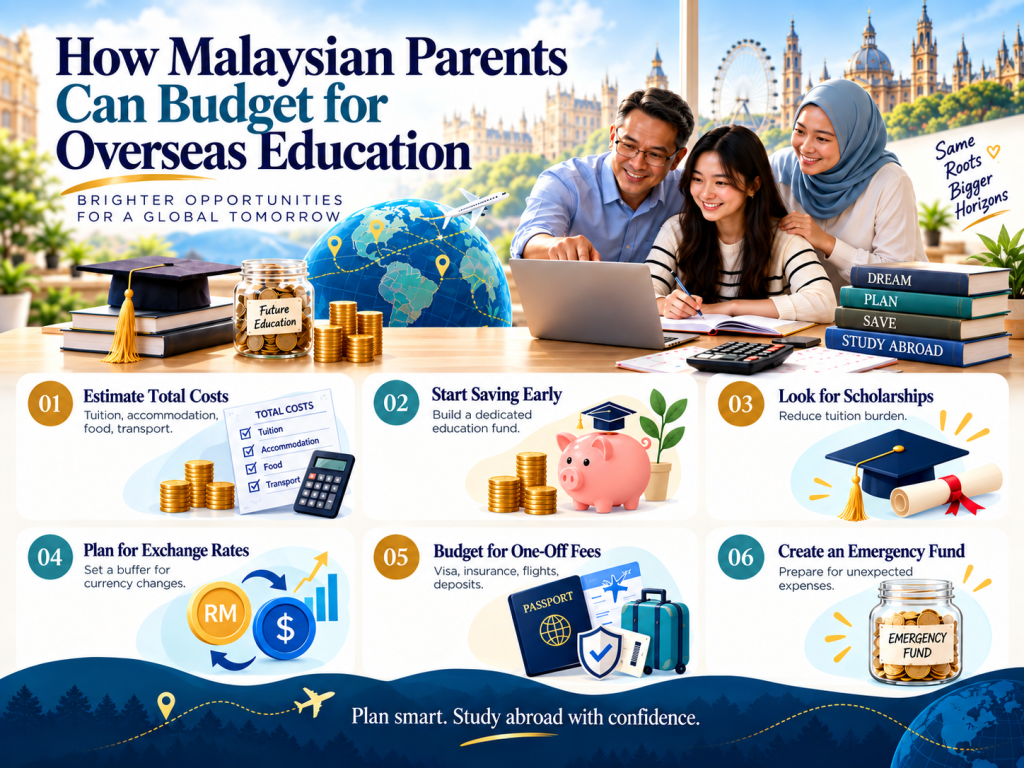
Budgeting for overseas education starts with separating tuition from everything else, because the everything-else is usually where families get caught out. A public university in the UK charges international students anywhere from GBP 15,000 to GBP 28,000 a year depending on the course — medicine and engineering sit at the top, humanities and social sciences lower down. Australia runs similarly, roughly AUD 32,000 to AUD 45,000 annually for a bachelor’s degree at a Group of Eight university like Melbourne or UNSW. Ireland’s public universities, such as Trinity College Dublin or UCD, typically charge EUR 20,000 to EUR 30,000 for international undergraduates. New Zealand sits a touch lower, around NZD 28,000 to NZD 38,000. Singapore is the outlier for Malaysians — NUS and NTU charge Malaysian citizens the ASEAN subsidised rate under the Tuition Grant Scheme, which can bring annual fees down to around SGD 17,000 to SGD 24,000, roughly half of what a non-ASEAN international student pays.
Then add living costs, which is the number most families underestimate. A student in London or Sydney can easily spend RM 4,500 to RM 6,000 a month on rent, food and transport; a student in a regional UK city like Coventry or a smaller Australian city like Adelaide might spend closer to RM 2,800 to RM 3,800. Dublin has become notably expensive for accommodation over the last two years, so budget on the higher end there. Staying in Malaysia — say, at Taylor’s, Sunway or Monash Malaysia — cuts the whole equation dramatically: total cost including living expenses for a three-year degree often lands between RM 90,000 and RM 150,000, versus RM 300,000 to RM 500,000+ for a full overseas degree in the UK or Australia.
Where to keep and grow the money you’re setting aside
Once you know the target number, the next question is where that money should sit while it grows. Malaysian parents typically use a mix of instruments rather than one account. Amanah Saham funds (ASB, ASM) remain popular because they’re accessible and historically stable, though allocation limits apply. The National Education Savings Scheme (SSPN-i) run by PTPTN is specifically built for this purpose and comes with modest tax relief on contributions — worth checking even if the amount is small, because every bit of relief adds up over a decade of saving. Fixed deposits and Amanah Saham are low-risk but low-growth; unit trusts or EPF Account 3 withdrawals (where eligible) give more growth potential but carry market risk, which matters a lot if your child is starting university in two years rather than ten. As a rough principle: the closer your child is to enrolment, the more the money should sit in something stable rather than something that could dip 15% the year before tuition is due.
Getting the exchange rate to work in your favour
Currency movement is the part of the budget parents feel most powerless about, and to some extent that’s fair — nobody can predict where the ringgit sits against the pound or the Australian dollar a year from now. What you can control is how you convert and send money. Wise, Instarem and similar remittance services generally beat the exchange rates offered by traditional banks by a noticeable margin, sometimes 1–3% on a large transfer, which on a RM 100,000 annual remittance is real money. Where possible, avoid converting the full year’s amount in one lump sum at a rate you don’t like; some parents split transfers across a few months to average out currency swings, similar to dollar-cost averaging. If your child’s university allows tuition payment in instalments, that also gives you more flexibility on timing than paying the full year upfront. Keep an eye on university-specific payment portals too — some, particularly in the UK, charge a card processing fee of 1.5–2% that a bank transfer avoids entirely.
Scholarships and grants that meaningfully reduce the bill
Scholarships for Malaysian students studying in Singapore under university-specific schemes, JPA sponsorships for selected fields, Yayasan Khazanah’s programmes, and university-specific merit scholarships in the UK and Australia can all shift the maths significantly — sometimes covering 25% to 100% of tuition. The mistake we see most often is families assuming scholarships are only for the “genius” student with a 4.0 CGPA; in reality, plenty of partial scholarships (RM 5,000 to RM 20,000 a year, or tuition fee waivers of 10–30%) are awarded on a mix of academic results, co-curricular involvement, and sometimes financial need. It’s worth applying even when your child’s results are solid-but-not-spectacular, because many of these awards have smaller applicant pools than students assume. Build scholarship research into your timeline at least 12 months before enrolment — most competitive awards close well before the university application deadline itself, not alongside it.
Setting aside a cushion for the unexpected
Even a well-built budget needs slack, because overseas education has a way of producing costs nobody put in the spreadsheet: a flight home for a family emergency, a laptop that dies in the first semester, a sudden jump in rent when a lease renews, or medical costs not fully covered by student insurance. We generally suggest parents hold back an emergency buffer equivalent to two to three months of living costs at the destination — so for a student in Australia, that might be RM 9,000 to RM 15,000 kept separately and not counted as part of the “spent” education fund. It’s also worth checking exactly what your child’s mandatory overseas student health cover (OSHC in Australia, or the NHS surcharge in the UK) actually includes, since dental, optical and some specialist care are often excluded and become out-of-pocket costs.
What to ask a consultant before you commit to a plan
A good consultant should be able to answer specific questions, not just reassure you. Ask what the total cost of the degree looks like across all four years, not just year one, since some universities raise international fees annually by 3–5%. Ask which scholarships your child actually qualifies for based on their real academic profile, not a generic list. Ask what accommodation typically costs near campus versus a 20-minute commute away, since that gap alone can be RM 1,000 a month. Ask about currency and payment logistics — does the university accept staged payments, and what do card fees look like. And ask, plainly, what happens if your child wants to switch course or university after year one, since transfer rules and cost implications vary a lot by country.
Frequently asked questions
How much should we save before starting the university application process? There’s no single figure, but most families aim to have at least the first year’s tuition and living costs secured, plus visa financial-proof requirements met, before applications go in — lenders and scholarship committees look more favourably on students who already show funding is in place.
Is it cheaper to do a diploma or foundation in Malaysia first, then transfer overseas? Often yes. Completing the first one to two years locally through a twinning or credit transfer arrangement can cut total costs by 30–50% compared to four years fully overseas, while keeping the same final degree and university name on the certificate.
Do scholarships cover living costs, or just tuition? Most cover tuition only, though a smaller number of fully-funded scholarships (particularly government-linked ones like JPA or Khazanah) include a living allowance. Always check the fine print before assuming a scholarship solves your full budget.
What’s a realistic monthly living budget for a student in the UK versus Malaysia? Roughly RM 4,000–5,500 a month in a major UK city versus RM 1,200–1,800 a month for a student living at home or in nearby student housing in Malaysia — a gap worth weighing seriously against the value of an overseas degree for your child’s specific goals.
If you’re at the stage of turning a rough number into an actual plan, that’s exactly the conversation GoUni consultants have with families every week, at no cost to you. Reach out through our contact page and we’ll go through your child’s target course, likely destinations, and a realistic budget together, based on the actual fee structures and scholarships available right now — not last year’s estimates.